Wage garnishment takes money directly from your paycheck before you see it. This happens when creditors win court judgments against you, and it can devastate your monthly budget.
We at Hurst Law Firm, P.A. know that stop wage garnishment steps exist, and many of them work fast. You have legal options that can halt garnishment immediately, from filing objections to exploring bankruptcy protection.
How Garnishment Actually Works in Tennessee
Creditors Win Judgments, Then Target Your Paycheck
Wage garnishment happens when a creditor wins a court judgment against you and then files a garnishment order with your employer. Your employer becomes legally required to withhold money from your paycheck and send it to the court. This process is not optional for your employer-they must comply or face penalties. The garnishment continues for six months and can be renewed repeatedly until the debt is paid.
Who Can Garnish Your Wages
Credit card companies, medical providers, and personal loan lenders commonly pursue garnishment through court judgments. Government agencies like the IRS and Tennessee Department of Revenue skip the court judgment entirely and garnish your wages directly. Child support and alimony have the strongest collection powers, reaching up to 50% of your disposable income if you have dependents, or 60% if you do not.
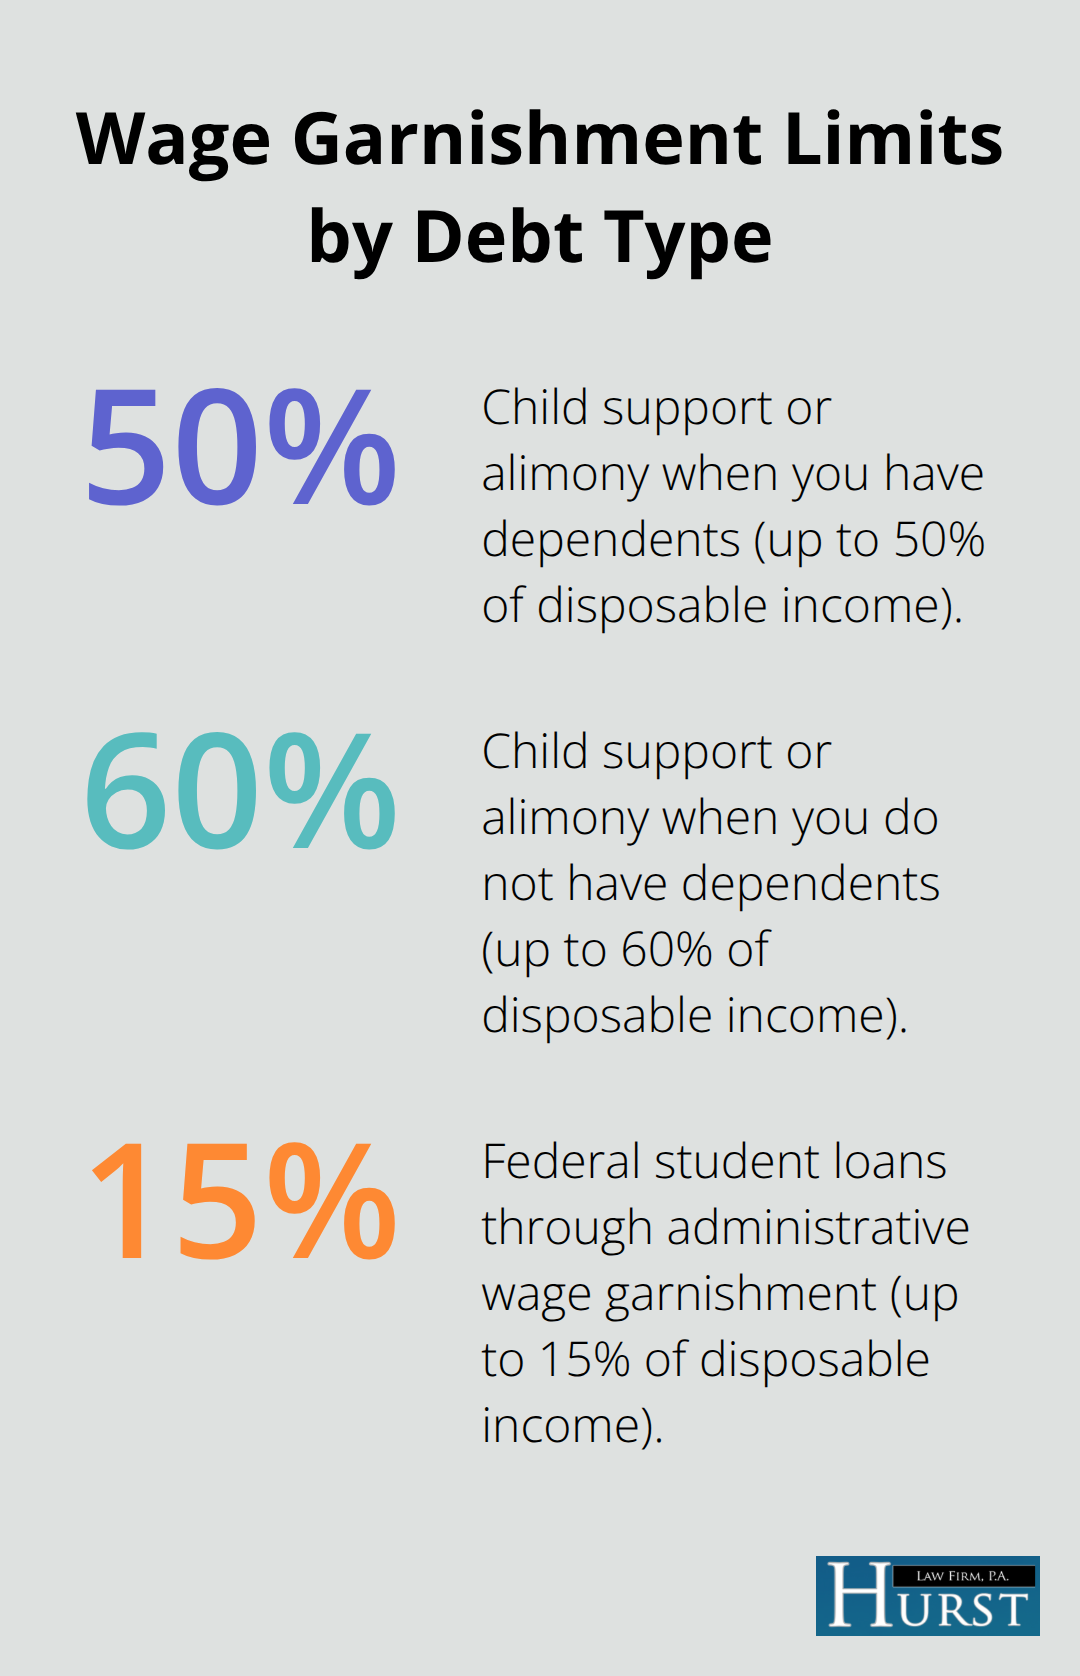
Federal student loans can also garnish up to 15% of your disposable income without a court judgment. Knowing exactly who targets your paycheck and what legal avenue they used matters because different debts have different rules.
Tennessee’s Garnishment Limits Protect Some Income
Tennessee law caps general consumer debt garnishment at 25% of your disposable earnings, but a critical floor protects lower-income workers. If your weekly disposable earnings fall below $217.50 (calculated as 30 times the federal minimum wage of $7.25), garnishment for general consumer debt typically cannot happen at all. Disposable earnings mean your take-home pay after legally required deductions like Social Security, Medicare, and taxes-not your gross salary.
Additional Protections for Families and Certain Income Types
Parents supporting minor children under 16 receive an additional $2.50 per week exemption per child if they file the proper declaration with their employer. Federal protections also shield certain income from most garnishments, including Social Security benefits, Supplemental Security Income, Veterans benefits, unemployment compensation, and workers compensation. Child support can still reach some of these protected sources, which is why understanding your specific income type matters before you act.
File an Exemption Claim Within 10 Days
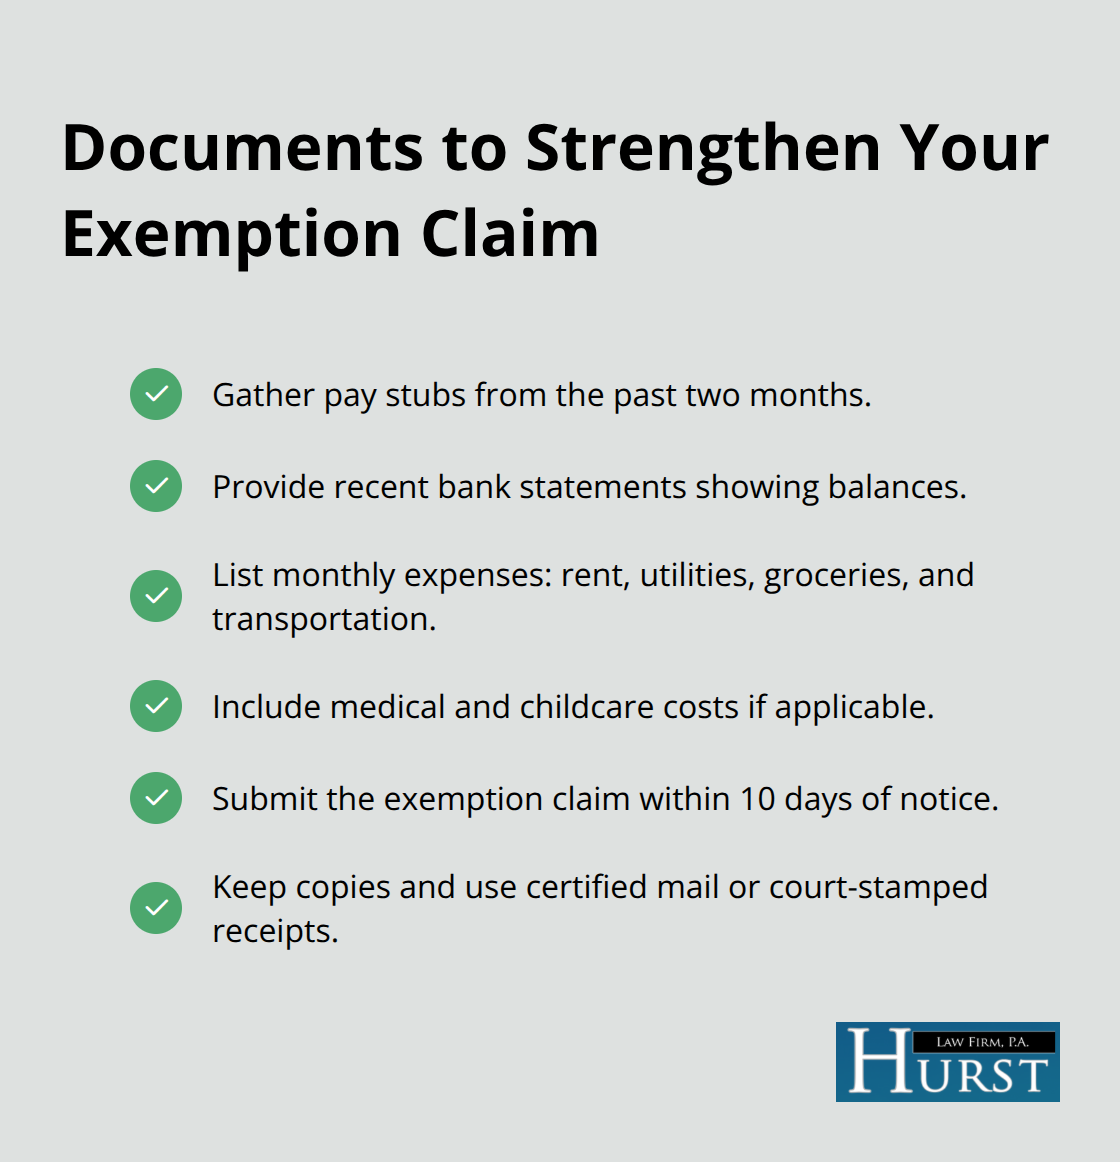
Many Memphis residents qualify for exemptions they never knew existed. Filing an exemption claim within 10 days of receiving the garnishment notice can reduce or stop the garnishment entirely. The court reviews your income, expenses, and family circumstances to decide if the garnishment exceeds legal protections. Bringing documentation of monthly expenses (rent, utilities, groceries, transportation) strengthens your case significantly. If the court grants your exemption, the garnishment stops or reduces, and any exempt money already withheld gets returned to you. However, if multiple garnishments target your paycheck or exemptions fail to provide relief, faster legal solutions exist that halt all collection actions at once.
Act Now Before Garnishment Drains More of Your Paycheck
The 10-Day Window After Garnishment Notice
Time matters more than most people realize when wage garnishment starts. Once your employer receives the garnishment order, money leaves your paycheck automatically every pay period until you take action. The first 10 days after receiving notice are your window to file an exemption claim, and waiting past that deadline closes one of your fastest options. You must submit your claim within 10 days of the garnishment notice, and the court will review your income, expenses, and family circumstances to determine if the garnishment exceeds legal protections.
Gather Documentation to Strengthen Your Exemption Claim
Filing an exemption claim requires specific documentation and strict timing. Collect pay stubs from the past two months, bank statements showing your account balances, and a detailed list of monthly expenses including rent, utilities, groceries, transportation, and any medical or childcare costs. The more thorough your documentation becomes, the stronger your case grows.
If the court grants your exemption, garnishment stops or reduces, and the employer must return any exempt money already withheld.
Negotiate Payment Plans Before Judgment Takes Hold
Contact your creditor directly if you have not yet received a court judgment-many will negotiate a payment plan before judgment happens, which stops garnishment before it starts. If you already face active garnishment, creditors sometimes accept direct payment arrangements, especially if you reach out within the first few weeks. A consistent payment history for three to six months can convince creditors to halt garnishment in exchange for a written agreement (which you should always obtain and verify through certified mail or bank drafts). Never commit to payment amounts you cannot sustain, because missed payments restart garnishment and add court costs and attorney fees on top of the original debt.
When Exemptions and Negotiation Fall Short
Exemptions only lower or stop garnishment-they do not eliminate the underlying debt. When facing multiple simultaneous garnishments or when exemptions provide insufficient relief, bankruptcy often saves the most money by stopping all collection actions at once. Filing for Chapter 7 or Chapter 13 bankruptcy triggers an automatic stay that halts wage garnishment within 24 hours of filing (this protection applies to all creditors except those collecting child support or alimony). Chapter 7 discharges most unsecured debts within three to four months, while Chapter 13 creates a three- to five-year repayment plan that halts garnishment and allows you to catch up on missed payments. The automatic stay works immediately, giving you breathing room to assess your full financial situation and determine which bankruptcy chapter fits your circumstances best.
Bankruptcy Stops Garnishment Faster Than Any Other Method
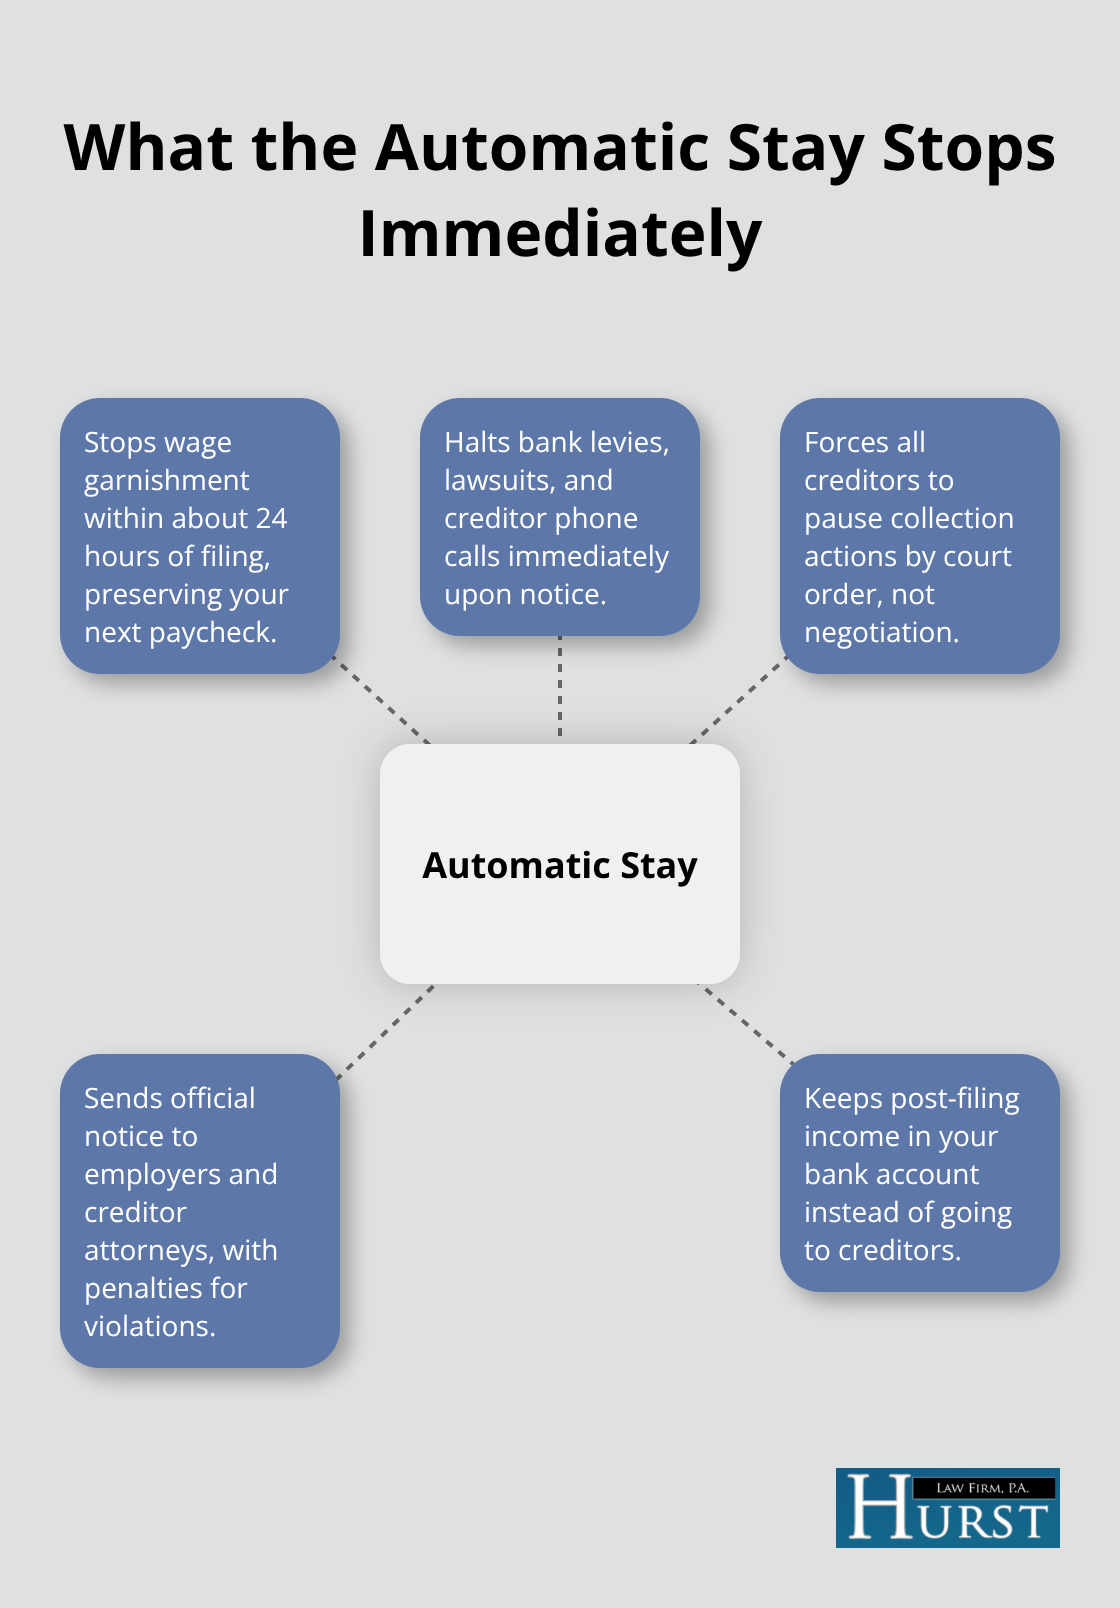
Filing bankruptcy in the U.S. Bankruptcy Court for the Western District of Tennessee triggers an automatic stay under 11 U.S.C. §362 the moment your petition is filed, and this stay halts wage garnishment within 24 hours. The automatic stay is not a request or a negotiation-it is a court order that forces all creditors to stop collection actions immediately, including wage garnishment, bank levies, lawsuits, and creditor phone calls. Employers and creditor attorneys receive official notice that the stay is in effect, and continuing garnishment after notice exposes them to penalties from the bankruptcy court. This immediate relief matters because every paycheck you receive after filing stays in your bank account instead of flowing to creditors.
How Chapter 7 and Chapter 13 Stop Garnishment
Chapter 7 bankruptcy discharges most unsecured debts like credit cards, medical bills, personal loans, and payday loans within three to four months, which eliminates the underlying judgment and stops garnishment permanently for those debts. Chapter 13 bankruptcy stops garnishment immediately and sets up a three- to five-year repayment plan, often used when you need to address tax debts, mortgage arrears, or when your income exceeds the Chapter 7 means test threshold. The means test compares your monthly income to the Tennessee state median income and calculates disposable income to determine Chapter 7 eligibility-if your income falls below the median, Chapter 7 becomes available without the means test calculation.
Filing Costs and Timeline
Filing costs are relatively low at $338 for Chapter 7 and $313 for Chapter 13, though attorney fees vary depending on case complexity and your financial situation. We at Hurst Law Firm, P.A. have been assisting the Memphis community since 1997 and can guide you through either chapter to determine which path protects your paycheck fastest.
Why Bankruptcy Beats Exemption Claims for Multiple Garnishments
If creditors have stacked multiple garnishment orders against your paycheck, bankruptcy stops all of them simultaneously while exemption claims only reduce individual garnishments one at a time. Filing bankruptcy also protects your bank account from levies, which means funds already garnished before filing may not be recoverable, but any funds in your account when you file remain protected. Chapter 13 is particularly powerful for stopping garnishment because the repayment plan keeps garnishment halted as long as the plan remains active, whereas Chapter 7 stops garnishment permanently for discharged debts but not for debts that survive the discharge like child support or most student loans.
Timing Your Filing Matters
The timing of your filing matters because the automatic stay applies to all creditors except those collecting child support or alimony, so if you face garnishment from multiple sources, filing before additional orders stack against you saves significantly more money over the life of your case.
Final Thoughts
You have three clear paths to stop wage garnishment steps from draining your paycheck. Filing an exemption claim within 10 days offers the fastest non-bankruptcy option if your income qualifies for protection under Tennessee law, while negotiating a payment plan directly with your creditor can halt garnishment before judgment takes hold. When exemptions fall short or multiple garnishments target your paycheck simultaneously, bankruptcy delivers the most comprehensive relief by triggering an automatic stay that halts all collection actions within 24 hours.
The financial impact of taking legal action now versus waiting compounds quickly-every paycheck you protect today stays in your account instead of flowing to creditors. Chapter 7 bankruptcy eliminates most unsecured debts within three to four months, while Chapter 13 restructures your obligations into a manageable three- to five-year plan. Both chapters stop garnishment immediately and permanently for discharged debts, giving you breathing room to stabilize your finances.
We at Hurst Law Firm, P.A. understand the urgency of your circumstances and can assess your case during a free consultation to identify which option protects your paycheck fastest. Contact us today to discuss your wage garnishment situation and explore the legal options available to you. The sooner you act, the sooner garnishment stops and your paycheck stays yours.